Common HPSEA Advice for Members Selling and Buying in One Move
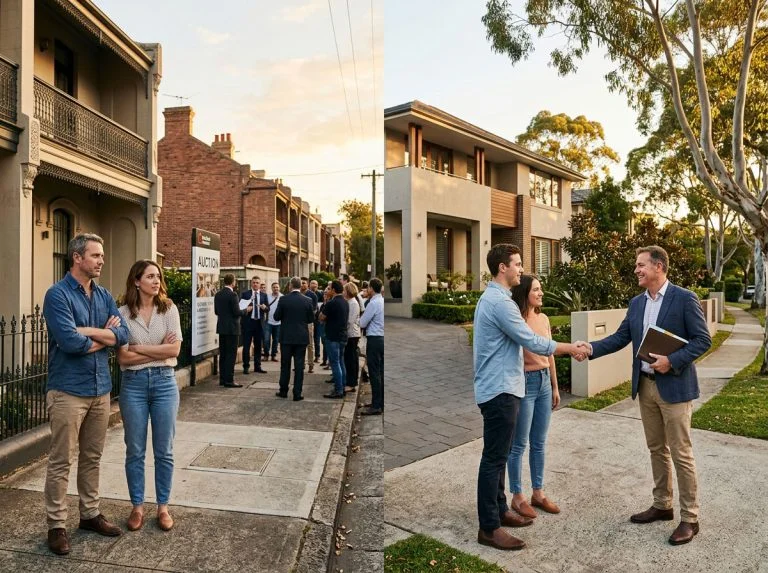
What does “selling and buying in one move” usually mean in Australia?
It means they sell their current home and buy the next one with settlement dates aligned closely enough to move once. In most states, that hinges on contract conditions, finance approval, and settlement timing.
Common HPSEA Advice for Members Selling and Buying in One Move is to plan for a small overlap or a short gap, because perfect alignment is rare.
Why do members try to do it in one move?
They usually want to avoid double moves, temporary storage, and short-term rentals. Many also want to limit holding costs such as two mortgages, rates, and insurance.
Common HPSEA Advice for Members Selling and Buying in One Move is to decide early whether saving money or reducing risk is the priority, because that choice shapes every step.
When should they sell first versus buy first?
Selling first can reduce financial risk because they know their sale price and settlement date. Buying first can secure the next home sooner, but it can increase pressure if their current place takes longer to sell.
Common HPSEA Advice for Members Selling and Buying in One Move is that most households prefer “sell first” unless they have strong borrowing capacity or bridging in place.
How can they set a realistic timeline for two transactions?
They can start by mapping three dates: listing-to-offer, contract-to-unconditional, and settlement-to-settlement. In Australia, settlement often ranges from 30 to 90 days, but it varies by state, lender, and negotiation.
Common HPSEA Advice for Members Selling and Buying in One Move is to build in buffer time, because finance approval and conveyancing steps can stretch unexpectedly.
What should they do before listing their current home?
They can organise a pre-sale appraisal, get conveyancing ready, and tidy up any documentation that slows a sale. It also helps to check likely marketing costs, auction versus private treaty strategy, and realistic price expectations.
Common HPSEA Advice for Members Selling and Buying in One Move is to do lender conversations early, so borrowing limits are clear before they commit to a purchase.
How should they structure their sale contract to protect their purchase plans?
They can negotiate a settlement period that gives enough time to find and secure the next property. If they expect to buy after selling, a longer settlement can create breathing room.
Common HPSEA advice for members selling and buying in one move is to avoid overly short settlement terms unless they already have a purchase secured and finance ready. Allowing enough time for coordinating property settlement dates can reduce pressure when both transactions depend on each other.
Can they use a “subject to sale” condition when buying?
In some Australian markets it is possible, but it can be less competitive, especially where demand is high. Sellers often prefer clean offers with fewer conditions.
Common HPSEA Advice for Members Selling and Buying in One Move is to treat “subject to sale” as a last resort and strengthen the offer in other ways if they need it.
How can they negotiate settlement dates so they only move once?
They can aim for same-day settlement or a tight handover, but it needs cooperation from both sides and their lenders. A more common approach is to sell with a later settlement, then buy with an earlier one that matches.
Common HPSEA Advice for Members Selling and Buying in One Move is to request settlement flexibility during negotiations rather than trying to force a single perfect date.
What is the role of bridging finance and when does it help?
Bridging finance can help if they buy before their sale settles, using the equity in the existing property temporarily. It can reduce the risk of missing out on a suitable home, but costs and approval criteria can be stricter.
Common HPSEA Advice for Members Selling and Buying in One Move is to treat bridging as a specialist product, confirm total repayments, and understand what happens if the sale price comes in lower than expected.
How can they reduce the risk of being stuck between settlements?
They can create a backup plan for both directions: if the sale settles late, or if the purchase settles early. Options include negotiating a licence to occupy, short-term accommodation, or storage for a limited period.
Common HPSEA Advice for Members Selling and Buying in One Move is to plan for at least one fallback, because a single delay can break the “one move” ideal.
What should they know about deposit rules and releasing funds?
In many Australian transactions, the deposit is held in trust and released at settlement, not earlier. That can matter if they want to use sale proceeds for the purchase deposit.
Common HPSEA Advice for Members Selling and Buying in One Move is to ask their conveyancer how deposits are handled locally and whether a deposit bond could be appropriate.
Should they use a deposit bond, and what are the trade-offs?
A deposit bond can help them buy without paying a cash deposit upfront, then use sale proceeds at settlement. It can be useful for tight timelines, but there are fees and eligibility checks.
Common HPSEA advice for members selling and buying in one move is to compare the bond cost against the benefit of keeping cash available for moving, repairs, and contingencies. Understanding the impact of posting dates can also help members plan their finances around the relocation timeline.
How should they coordinate conveyancing and loan approvals?
They can ask their conveyancer and broker to share key dates, special conditions, and finance milestones. Many delays come from missing documents, valuation hold-ups, or unclear contract clauses.
Common HPSEA Advice for Members Selling and Buying in One Move is to keep all instructions in writing and confirm deadlines weekly once contracts are signed.
What due diligence can they complete without slowing the process?
They can order building and pest inspections quickly, review strata records if relevant, and clarify inclusions and exclusions before signing. For auctions, they can do most checks upfront since the contract is usually unconditional on the day.
Common HPSEA Advice for Members Selling and Buying in One Move is to prioritise the checks that could stop the deal, then move fast on the rest.
How can they handle moving logistics if same-day settlement is tight?
They can book movers with a flexible window, pack early, and plan for access times that suit both properties. Some movers offer “settlement day” staging where items are loaded, then delivered once keys are released.
Common HPSEA Advice for Members Selling and Buying in One Move is to assume keys may be later than expected and budget for extra hours, because bank processing and final confirmations can run long.
What costs do they often overlook when selling and buying together?
They may forget overlapping insurance, council rates adjustments, utility connections, cleaning, minor repairs, and storage. Stamp duty timing also matters, particularly if they expect sale proceeds to cover purchase costs.
Common HPSEA Advice for Members Selling and Buying in One Move is to create a single combined budget for both transactions, not two separate ones, so cash flow gaps are visible.
How should they manage emotional pressure and decision fatigue?
They can set clear non-negotiables for the next home, then stop inspecting options that do not fit. Rushed decisions often happen when they fear missing settlement alignment.
Common HPSEA Advice for Members Selling and Buying in One Move is to decide on a maximum acceptable compromise ahead of time, so choices stay rational under time pressure.
What communication habits keep two transactions on track?
They can keep one shared timeline, confirm updates after every key milestone, and ask direct questions when something is unclear. It helps if they nominate one point of contact in each professional team, such as the broker and conveyancer.
Common HPSEA Advice for Members Selling and Buying in One Move is to treat silence as a risk and follow up early, because small delays compound quickly when two settlements must line up.
What is a practical “Plan B” if one move becomes two?
They can plan for temporary accommodation, short-term storage, and a simple essentials kit for a week or two. In Australia, short-stay options range from serviced apartments to holiday rentals, depending on location and season.
Common HPSEA Advice for Members Selling and Buying in One Move is to price Plan B before they need it, so they can choose the least disruptive option quickly if timelines shift.
What should they do in the final week before settlement?
They can confirm settlement bookings, check final figures, complete final inspections, and ensure movers are locked in. They can also prepare identification and any bank requirements for the day.
Common HPSEA Advice for Members Selling and Buying in One Move is to double-check inclusions, keys, and access arrangements, because last-minute surprises often come from assumptions rather than major legal issues.
How can members make the whole process smoother from the start?
They can start with finance clarity, realistic sale pricing, and a timeline that includes buffer. They can also choose professionals who handle high-volume settlement coordination in their state and communicate clearly.
Common HPSEA Advice for Members Selling and Buying in One Move is to aim for “controlled flexibility” rather than perfection, because a calm, well-structured plan usually beats a rushed one-move ideal.
FAQs (Frequently Asked Questions)
What does “selling and buying in one move” mean in the Australian property market?
Selling and buying in one move means selling your current home and purchasing the next one with settlement dates aligned closely enough to enable a single move. In Australia, this depends on contract conditions, finance approval, and settlement timing. It is common to plan for a small overlap or short gap as perfect alignment is rare.
Why do homeowners prefer to sell and buy in one move?
Homeowners usually aim to avoid double moves, temporary storage, short-term rentals, and reduce holding costs such as paying two mortgages, rates, and insurance simultaneously. Deciding early whether saving money or reducing risk is the priority helps shape every step of the process.
When should I sell first versus buy first when coordinating both transactions?
Selling first reduces financial risk by confirming your sale price and settlement date. Buying first can secure your next home sooner but increases pressure if your current property takes longer to sell. Most households prefer selling first unless they have strong borrowing capacity or bridging finance arranged.
How can I set a realistic timeline for selling my current home and buying a new one?
Start by mapping key dates: listing-to-offer, contract-to-unconditional, and settlement-to-settlement. Settlement periods typically range from 30 to 90 days depending on state laws, lenders, and negotiations. It’s advisable to build buffer time as finance approval and conveyancing steps may take longer than expected.
Can I use a “subject to sale” condition when buying a property in Australia?
While possible in some markets, “subject to sale” conditions can make offers less competitive since sellers often prefer clean offers without conditions. It’s best treated as a last resort; strengthening your offer in other ways improves chances of success when buying and selling simultaneously.
What role does bridging finance play when selling and buying in one move?
Bridging finance helps if you purchase before your current sale settles by temporarily using equity from your existing property. It reduces the risk of missing out on a suitable home but comes with stricter approval criteria and additional costs. Treat bridging finance as a specialist product; understand total repayments and risks if your sale price is lower than expected.